The Myths of Pricing
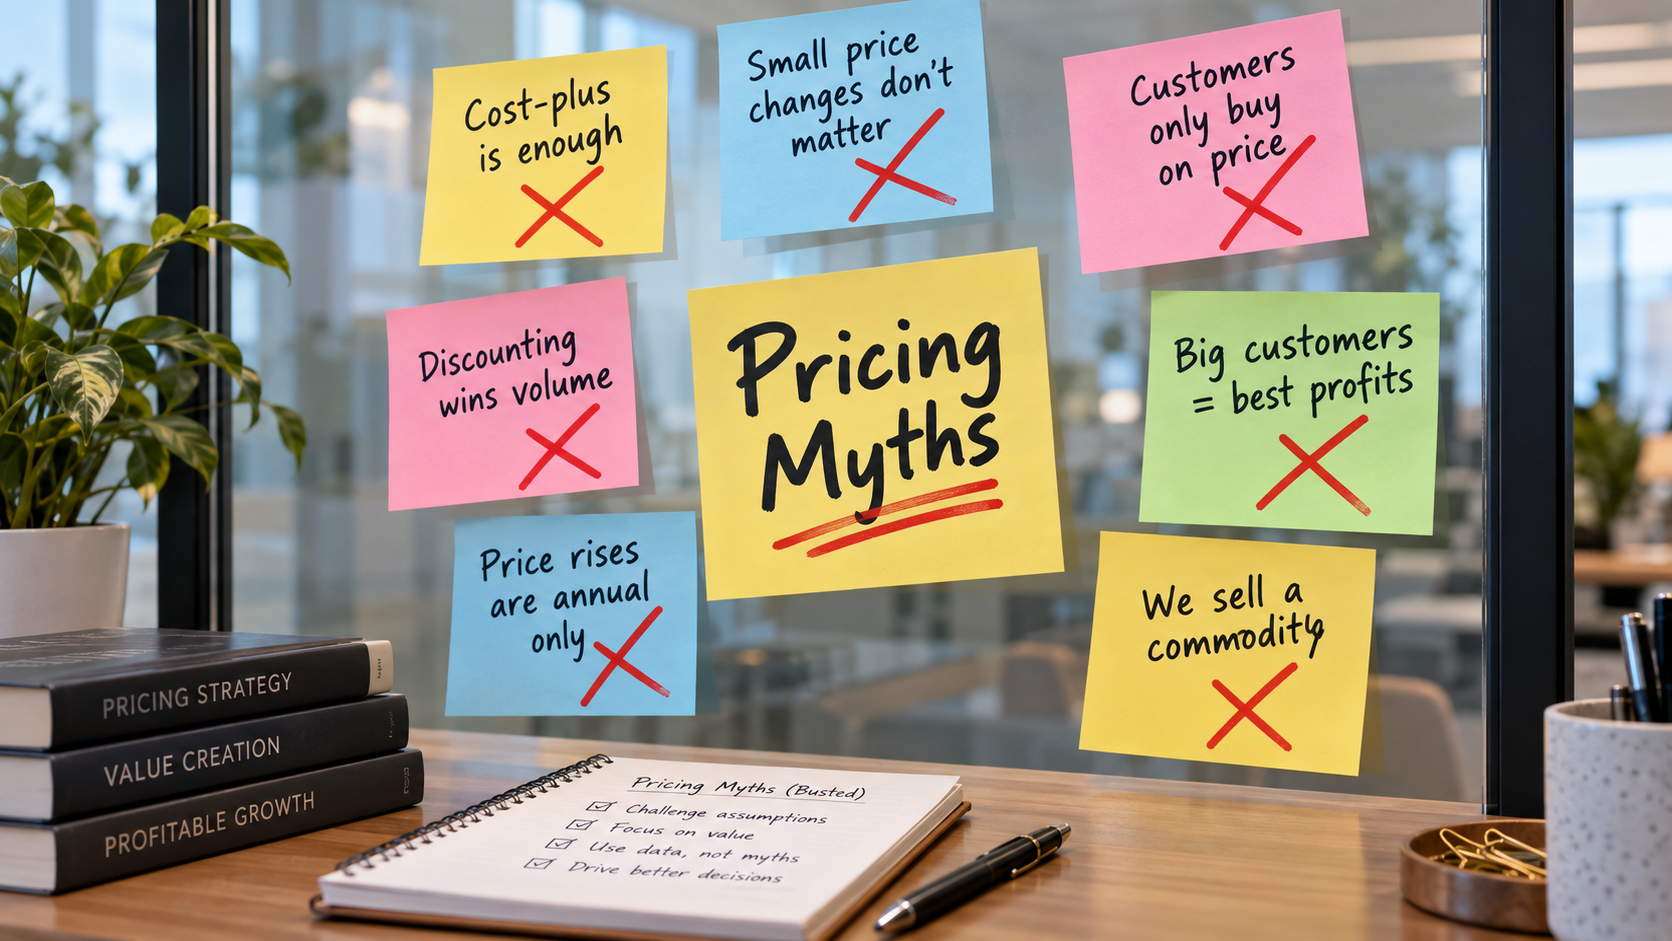
There are many myths about pricing. Probably as many as there are about every other business topic!
The difference with pricing is the outsized impact it has on the bottom line. That makes understanding the reality of each myth incredibly important.
What are some common myths?
Universal myths
Cost-plus is good enough
Small price changes have little impact on profits
Customers only buy on price (so there is a market price)
High market share automatically leads to high profits
Discounting wins volume
Price increases are an annual exercise
What we're selling is a commodity
B2B myths
B2B buyers are purely rational, and only look at the facts in front of them
Dynamic pricing is only for airlines, hotels and Uber
Sales reps know exactly what the client will accept as a price
Our biggest customers are our most profitable
If we increase our prices we'll lose too many customers
A high win-rate means we're priced about right
B2C myths
Changing prices too often will alienate customers
Bundling extras always increases a customer's willingness to pay
Loyalty tiers always increase margins and retention
Let's explore each of these in more detail.
Universal myths
1. Cost-plus is good enough
Cost-plus is a very simple approach. Add together all the costs for a product or service, then add a fixed mark-up. The mark-up is calculated to cover all costs and provide a target net margin.
The advantages of cost-plus are simplicity and protection. Simplicity, because it's quite easy to calculate a price; and protection, because (if done accurately) it should ensure that prices never drop to the point where a loss is being made.
But it has some serious weaknesses.
First, the mark-up needs to be calculated to cover overheads, and that calculation rests on an assumption about volumes. If volumes change, the overhead carried by each unit changes too, and the mark-up needs to be recalculated. If volumes fall and no one notices, prices can quietly stop covering costs.
Second, if input costs go down, the price goes down. That's an opportunity to increase margin that has just been lost.
Third, and most importantly, it ignores any differentiation, or the value being delivered. Two products with identical costs can be worth very different amounts to a customer, but cost-plus prices them the same. It therefore leaves margin on the table.
Finally, there's a cultural cost. Sales teams become lazy about communicating value (which helps to close more deals or make more sales) because no one in the company thinks about value, only about costs.
A paper in 2008 by Andreas Hinterhuber (Customer value-based pricing strategies: why companies resist) showed that it was the ease of use that made it popular, despite it being one of the least effective (from a margin point of view) approaches to pricing.
The mitigation is to move to value-led pricing and value-led communications. Costs obviously still matter, the company should always know the minimum price it needs to charge to be profitable, but the thinking should all be about customer value.
2. Small price changes have little impact on profits
This myth is usually due to a lack of understanding of finances, or a complacency which allows pricing to be ignored.
In fact, if net profit is 10%, and prices are increased by 1%, then if volumes and costs don't change the net profit is now 11% (roughly), which is a 10% improvement.
It works the other way too. A 1% price cut, with no change in volume, knocks the same 10% off profit. Because every extra penny of price goes straight to the bottom line, price is almost always the most powerful profit lever a business has – more powerful than an equivalent improvement in volume or costs.
A classic paper on this was Marn & Rosiello’s in 1992 in Harvard Business Review called Managing price, gaining profit. A 1% price improvement lifted operating profit by around 11% across a large sample of companies, more than equivalent gains in volume or cost. The paper also introduced the concept of the pocket price waterfall.
The mitigation here is financial training for all customer-facing team members with authority to vary prices, and especially whoever sets price lists.
3. Customers only buy on price (so there is a market price)
The appeal of this myth is that it simplifies the sales process – lower the price and convert the opportunity.
Companies think this is how customers think and act, but ignore that they themselves don't act that way – so why should their customers be different?
This is closely rotated to the myth that the market sets the price. This is usually just fear that, if you try to differentiate and charge more, customers will just buy the cheapest, so everyone copies everyone else.
There is also the potential to trigger a price war. When one company does lower prices to win sales, competitors follow suit, and then it's almost impossible to raise prices again.
In B2C and retail markets, this is self-evidently not the case. Brand is massively important. In one test in a TV documentary in the 1990s, teenagers were asked what they would be prepared to pay for a pair of jeans, choosing between Levi's branded jeans and unbranded ones – they paid twice as much for the Levi's. Except the unbranded jeans were actually Levi's with the brand removed.
Even in B2B markets the decision is often about least risk or best value delivered, balanced against price, not just the lowest price possible.
What’s the evidence? The literature is awash with research that backs up the statement that customers buy on more than price, such as Samuel McClure (Neural correlates of behavioral preference for culturally familiar drinks) who in 2004 compared preferences for Pepsi and Coke, or Hilke Plassman et al in 2008 (Marketing actions can modulate neural representations of experienced pleasantness) who showed that the same wine was rated higher by drinkers when they were told it cost more.
How to mitigate? Understand your value (both actual value and brand value), and clearly communicate it. Differentiate, and look for areas of distinctiveness.
Does this work?
One client of mine provides a home repair service. There were three big national players, all with similar prices, so everyone else matched them. We identified my client's value, increased their price by 13% based on the extra value delivered, and clearly communicated the value – no change in demand whatsoever.
4. High market share automatically leads to high profits
Market share has its advantages – massive brand awareness, economies of scale, and entry barriers against smaller new competitors.
But it depends on what you had to do to get that market share. If you won it through discounting, then no. You've bought the volume with your margin, and as soon as your prices go up again all the cost-sensitive customers who are looking for the best deal go away again. If you've got it because of the strength of your brand (think iPhone), then yes. Apple's share of smartphone industry profits has consistently been far larger than its share of phones sold.
Again, what does the research tell us?
Scott Armstrong and Fred Collopy’s 1996 paper (Competitor orientation: effects of objectives and information on managerial decisions and profitability) studied companies and showed that those that focus on market share rather than profits were less profitable and more likely to fail. Their conclusions were reinforced in 2018 through the work of Alexander Edeling and Alexander Himme (When does market share matter? New empirical generalizations from a meta-analysis of the market share–performance relationship) which concluded after a huge meta-analysis that chasing market share had the lowest impact on margin compared to any other metric.
In this case the mitigation is to focus on something other than sales volume, such as gross margin, net margin or economic value add. Market share can be a useful metric for a business, but it should be a result of good pricing rather than the goal.
5. Discounting wins volume
Discounting often wins volume temporarily (see my previous point about high market share).
But all it tends to do is attract the most price-sensitive customers, who then go elsewhere as soon as the discount ends.
If continued, then discounting becomes a habit within the business, which significantly degrades margin.
For example, one retailer I worked with had grown from £10m turnover making around £1m profit to £20m turnover making £200k profit, because discounting became the default way they won all business. So yes, for them, discounting drove volume, but it seriously damaged the business’s profitability.
In addition, you are training your regular customers to either wait for another discount-led campaign or to always ask for (and expect to get) a lower price. This not only seems intuitively obvious, it is backed up by research. For example, in 1997 Carl Mela et al (The long-term impact of promotion and advertising on consumer brand choice) showed that over time, promotions just make customers more price-sensitive.
The mitigation is not to stop discounting altogether, but to treat discounting as a tool, not a habit. Every discount should have a clear purpose (clearing stock, winning a strategic account, stimulating demand in a quiet period), a defined end date, and a clear understanding of how much extra volume is needed to pay for it. It should also always be crystal clear to the customer that the lower price is temporary. And if there is a regular reason to try to drive more sales, such as a seasonal drop in the summer, don’t just have a Summer Sale every year – you are again training your customers to wait for the bargain. Instead, vary the campaign – some years use a sale, some years bundle some elements of additional service, some years do something like a product launch, etc.
6. Price increases are an annual exercise
Well, annual sometimes. For some companies it's less often than that!
Pricing should be reviewed regularly, and annual is only a minimum. Between reviews, it helps to have pricing assessment triggers. For example, measure your win/loss ratio, and if you start to win too many contracts, then increase the price again. One company in one of my audiences, when asked about price increase frequency, estimated that it was roughly every 9 months because this is exactly what they did.
If pricing is simply an annual event – prices go up every 1st January – then there is a danger that margin erodes between those annual events, especially when there is a lot of volatility in the economy.
The mitigation is to have clear measures, such as changes to input costs, changes to competitor activity, changes to market conditions, changes to sales performance, etc, that trigger a price review.
7. What we're selling is a commodity
If you are genuinely selling a commodity, then that simplifies pricing a lot! There's no need for specialist marketing or to work out what value is being delivered. All you have to do is focus on operational efficiency and scale.
I used to say that there aren't really many genuine commodities. Perhaps if you're selling road aggregate, then one stone is like another and it's a genuine commodity. But most companies can find ways to add value and differentiate.
Here are some examples where 'commodity' market players have differentiated:
A printer. Their volume comes from 'commodity' items such as business cards and leaflets, which cover the machine running costs. But they have a specialist arm that does secure document printing, such as passports, and that's where they make all their margin.
Another printer. The same 'commodity' items cover machine overheads. But they've developed their own range of posters for a specialist market – and again, that's where they make their margin.
An electronics component broker. If you're not aware of what a component broker does, they buy excess electronics components from one manufacturer who has a surplus and sells them to another who has too few for their production plans. It is an almost perfect commodity market – each component is completely fungible. A Samsung memory chip of a specific type is 100% identical to the same chip from someone else, so when a manufacturer needs them, the lowest price wins. But this broker has developed software to connect manufacturers together and they are now creating a market between those manufacturers, where the broker makes a margin on each transaction.
But surely aggregates, as I said earlier, are just sold on price?
I recently spoke to a company that sells aggregates, and discovered that even they have specialist areas where they can differentiate and add value, such as stone for resin-bonded driveways. So even in the case of the example I have been using for years of a true commodity, there are opportunities to differentiate and provide value-added products or services.
I’m in good company. Theodore Levitt, back in 1980, argued exactly the same thing in Harvard Business Review (Marketing success through differentiation – of anything) - there is no such thing as a commodity, everything can be differentiated through packaging, service or some other element.
Mitigation should be obvious: always focus on finding ways to add value and differentiate; and if that’s genuinely impossible then embrace the market you are in and excel at operational efficiency at the lowest cost.
Final thoughts
Every one of these myths has a grain of truth in it, which is exactly why they persist. Cost-plus does protect against losses. Discounts do win volume. Big customers do bring scale.
The problem is when the grain of truth becomes the whole story, and pricing decisions get made on habit, fear or assumption rather than evidence.
The common thread through almost every mitigation is the same: understand the value you deliver, measure what's actually happening, and have the confidence to price accordingly.
If you want to receive these monthly blogs direct to your inbox then subscribe to my monthly pricing bulletin – simply send me an email from the email account you want the bulletins to go to with a subject line ‘SUBSCRIBE’.